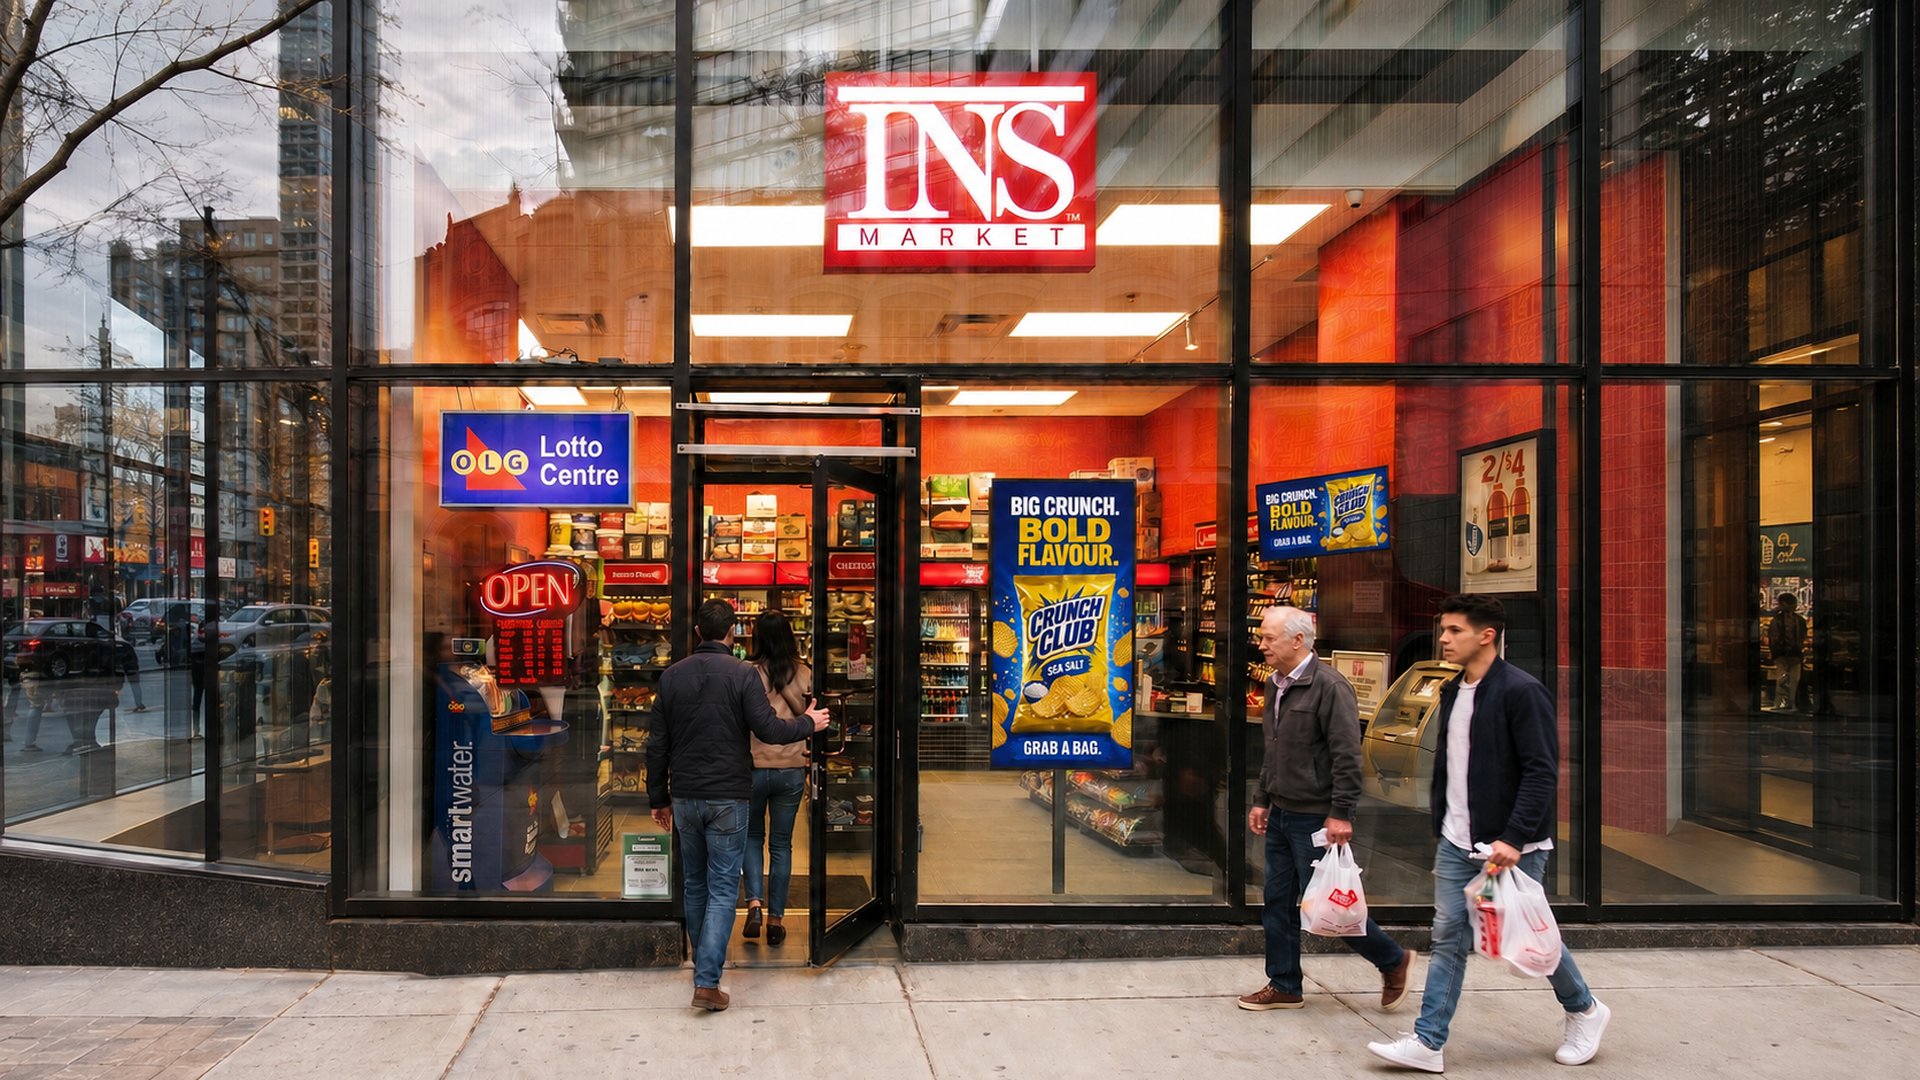
21.8 million Canadians aged 14 and older shopped a convenience store in the past 30 days.1 That is 60.6% of the population, in one retail channel, every month. Yet convenience store advertising in Canada is still treated as a top-up buy, booked after TV, social and transit are locked. The audience data says it belongs earlier in the plan. Here is what the numbers show.
Who Shops Convenience Stores in Canada Every Month
Convenience is not a niche audience. Vividata’s Spring 2026 Study of the Canadian Consumer puts monthly convenience store shoppers at 21.8 million Canadians 14+, or 60.6% of the population.1 Widen the window to the past 6 months and the figure reaches 23.0 million, or 63.9%.1
The gap between those 2 figures is useful. About 1.2 million Canadians shop convenience occasionally but not every month. The other 21.8 million come back inside 30 days, which is what makes convenience a planning channel rather than a seasonal one.
That 21.8 million is not 1 demographic. It is most of the country, measured at a single type of store. Planners usually buy commuters, students, families and shift workers through separate channels. In convenience, they share the same counter.
For brand marketers in beverage, snacks, CPG and telecom, that changes the starting question. It is no longer whether the audience is big enough. It is how often you can reach it.
Convenience Store Advertising Builds Frequency, Not Just Reach
Reach gets a plan approved. Frequency gets a message remembered. Convenience delivers both.
7.0 million Canadians visit a convenience store 6 or more times a month, 19.4% of the population.1 Within that group, 2.3 million heavy shoppers visit 11 or more times a month.1 For those shoppers, the store is close to a daily habit, and every visit is another chance to see a screen at the counter.
That is where footprint matters. Adapt Media pairs national convenience coverage across 10 provinces and 3 territories with neighbourhood-level targeting, a combination few DOOH networks offer. The same logic drives neighbourhood DOOH: Canadians shop close to home, and the screens closest to home see them most often.
A frequency channel also changes how a flight should be judged. A 4-week convenience buy is not 1 impression per shopper. For the 7.0 million frequent shoppers, it is repeat exposure built into a routine they already have.
Visits Are Growing Because New Shoppers Are Walking In
Monthly convenience store visits grew 26.4% between Winter 2024 and Spring 2026, from 92.1 million to 116.5 million visits a month.2 Over the same period, the average shopper’s trips held steady at about 5.3 visits a month.2
Read those 2 numbers together. Trips per shopper barely moved, so the growth came from more people walking in. The channel is adding audience, not squeezing more trips out of the same customers.
That matters for planners comparing channels. Convenience visit volume is growing, and the audience at the counter in 2026 is larger than it was 2 years ago. A planner who last looked at convenience in 2024 is working from a smaller audience than the one that exists today. Category shifts add to the case. In Ontario, beverage alcohol has already moved into convenience, a change covered in our look at convenience store alcohol sales in Ontario.
Where Convenience Ranks Among Out-of-Home Environments
Shoppers notice the advertising. 4.5 million Canadians, 12.4% of the population 14+, saw advertising in a convenience store in the past week.1 Convenience stores rank 7th of 26 named out-of-home environments for advertising seen in the past week, ahead of quick service restaurants, subway, elevators, airports and sports venues.1
The pattern holds across regions. In Ontario, 1.8 million people saw advertising in a convenience store in the past week, 12.4% of the province’s population 14+. In Alberta, the figure is 499,000, or 12.1%.1 Digital screens alone reached 1.5 million Canadians in the past week.1 That is the digital-only slice of the audience, and it is the part a programmatic or dynamic creative plan can reach directly.
Out-of-home as a whole is also growing. Canadian out-of-home advertising revenue grew 5.8% in 2025.3 Convenience sits inside that growth with an audience that is both broad and habitual.
For a planner, the ranking answers a practical question. Convenience is not an untested format that needs a pilot to prove people look at it. It already outranks environments that routinely make national plans.
How Planners Use Convenience Store Reach and Frequency
Research on in-store screens shows where the effect is strongest. A study of 237 digital signage campaigns and 30 million shoppers found in-store digital signage raised the likelihood of buying the featured product by 8.1%.4 The lift was larger for low-priced and impulse products, in crowded stores, with emotional creative, and when the screen sat near the advertised product.4 The study did not measure Canadian convenience stores specifically, so treat the 8.1% as directional.
That profile reads like a description of convenience: low-priced items, impulse decisions, and a screen at the counter where the decision happens. 3 moves follow from it:
- Plan convenience for frequency. Use it to build repeat exposure among the 7.0 million frequent shoppers, not as a one-off reach top-up.
- Match creative to the moment. Short, emotional, product-forward creative suits a counter screen better than a long brand story.
- Model it alongside other out-of-home. Reach and frequency modelling for out-of-home inventory is now available in Canadian industry planning tools,5 so convenience can be planned with the same discipline as the rest of the mix.
Timing helps too. The study found stronger effects on weekends and later in the day.4 Many convenience stores keep longer hours than other retail, which gives a planner more of those windows to work with.
Start from the audience, not the format. An audience-first OOH planning method puts convenience in the plan when the target shops there often, which for most mass brands is a large share of the country.
Reach and frequency are the first half of the case. The next questions are where the budget comes from and how to show it worked. The next 2 posts in this series take on each.
References
- Vividata. “Study of the Canadian Consumer, Spring 2026, Total Canada 14+
- Vividata. “Study of the Canadian Consumer, Total (Volume): Winter 2024 (P2024Q11) and Spring 2026 (P2026Q21)
- COMMB via Sixteen:Nine. “Canadian OOH Ad Revenues Grow 5.8% As Mobility And Experiences Drive Media Exposure.” https://www.sixteen-nine.net/2026/03/18/canadian-ooh-ad-revenues-grow-5-8-as-mobility-and-experiences-drive-media-exposure.
- Herhausen, de Jong and Grewal, Journal of Marketing. “In-Store Advertising with Digital Signage, vol. 90, no. 3, 2026, pp. 91 to 103.” https://doi.org/10.1177/00222429251351578.
- COMMB via Media in Canada. “COMMB enhances Roadmap with a new reach and frequency tool.” https://mediaincanada.com/2025/05/28/commb-roadmap.